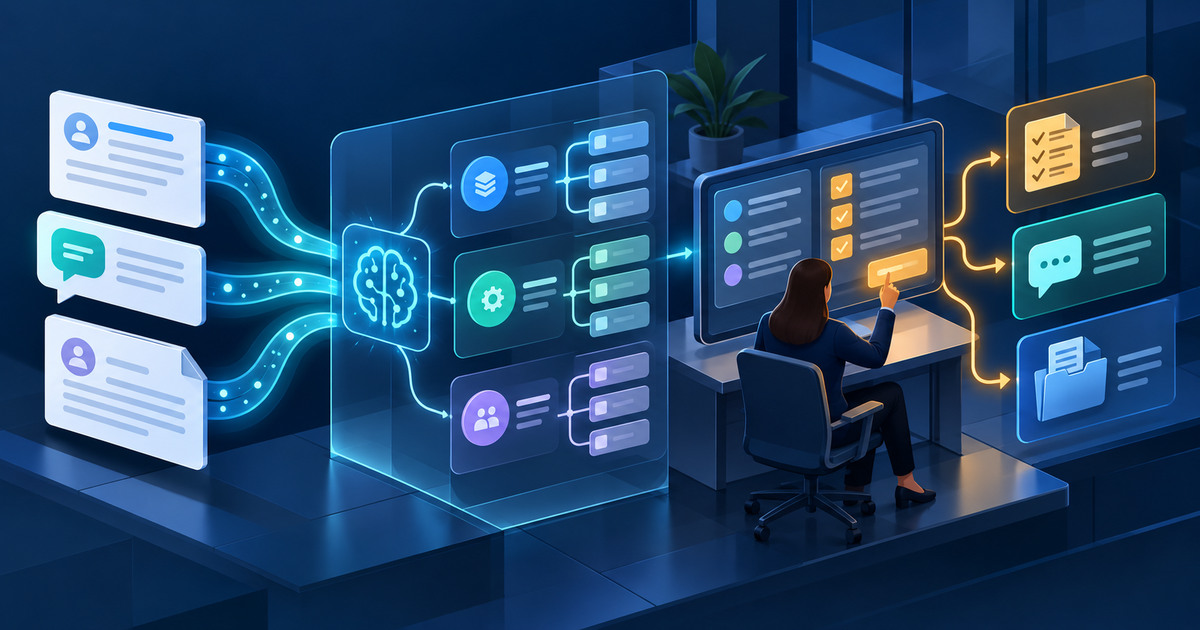
Complaint analysis is an attractive credit-union AI use case. Narratives arrive through branches, contact centers, email, chat, surveys, social channels and regulators. A model can normalize language, suggest categories, link similar cases and flag an emerging pattern before a monthly report would reveal it.
That efficiency creates a tempting shortcut: treat the model’s label as the complaint determination, the cluster as the root cause, or the generated summary as the case record. Those moves collapse three different jobs. Triage organizes work. Investigation establishes what happened. Remediation decides what the member and the institution need next.
The NCUA Consumer Assistance Center process relies on case details, supporting records, written responses, resolution windows and an appeal path. The CFPB Consumer Complaint Database is useful for market context, but the Bureau cautions that it is not a statistical sample and that volume should be interpreted with company size and other data. The NIST AI Risk Management Framework provides a practical discipline for governing, mapping, measuring and managing the AI layer. Together, those sources point to a design in which automation supports evidence handling without becoming the authority for a member’s case.
1. Define the complaint boundary before automating intake
Start with a written definition of complaint, inquiry, dispute, error notice, fraud claim, service request and appeal. The same member message may trigger more than one workflow. A card transaction complaint can also be a Regulation E claim; a credit decision complaint can raise fair-lending or adverse-action questions; a servicing narrative may require immediate escalation even when the member never uses the word “complaint.”
Give the model a routing job, not a jurisdiction job. It may propose one or more categories, urgency and a responsible team. It should not decide that a message falls outside a legal or policy process. Preserve the original language and attachments before any summary or redaction step.
Evidence: approved taxonomy, multi-route rules, excluded determinations, original record hash, source channel, received time and accountable owner.
2. Separate extracted facts from generated interpretation
Each case record should distinguish what the member said, what the credit union’s systems show, what the model inferred and what an investigator concluded. Store verbatim dates, amounts, product names, transactions and cited communications next to the source. Put summaries, sentiment, probable issue and suggested next action in clearly labeled fields.
Require every material generated assertion to point back to the underlying record. If the system cannot cite the source span or transaction, the assertion is a lead for review—not evidence. Do not allow a polished summary to replace the documents needed to reconstruct the case.
Evidence: source-to-summary citations, extraction confidence, missing-field flags, conflicting facts, reviewer corrections and retained originals.
3. Route by harm and clock, not only by topic
A useful triage model prioritizes the consequence of delay. Add deterministic rules for potential unauthorized transactions, foreclosure or repossession risk, account lockout, loss of access to funds, identity theft, elder exploitation, active discrimination allegations, recurring fees and missed regulatory response dates. Those rules should operate even when the model is unavailable.
Track at least three clocks: time since receipt, time to a meaningful member response and time to final resolution. A fast acknowledgment does not cure a stalled investigation. Escalate both high-harm cases and ordinary cases that age beyond policy.
Evidence: harm factors, regulatory and policy deadlines, priority reason, queue age, escalation trigger and handoff acknowledgment.
4. Validate clusters before declaring a root cause
Topic clustering can reveal repeated descriptions that staff would otherwise read separately. But similarity is not causality. Ten complaints about delayed deposits may arise from one release rule, a vendor outage, confusing disclosures, branch training, fraud holds or several unrelated events.
Require a named analyst to test a cluster against operational data. Join complaints to product version, transaction type, channel, vendor, policy, location, release, outage and prior change records. Sample cases inside and outside the cluster. Compare the apparent pattern with a denominator such as transactions, active accounts or completed applications. Record alternative explanations and the evidence that confirms or rejects them.
Evidence: cluster version, included and excluded cases, denominator, operational joins, competing hypotheses, validated cause and approving analyst.
5. Keep remediation authority outside the model
The AI may assemble relevant policy, prior remedies and estimated exposure. It should not approve credits, reverse a decision, waive a right, make a legal conclusion or close a complaint. Define monetary and nonmonetary remedy authority by role, with a separate path for systemic harm.
When one complaint reveals a broader problem, remediation should extend beyond the visible case. Determine the affected population, time period, products and channels. Recalculate harm from authoritative systems, not from a language-model estimate. Document member notification, correction, fee or interest treatment, credit reporting, vendor recovery and confirmation that the fix reached every identified account.
Evidence: remedy matrix, approver, member-specific calculation, affected-population query, quality sample, completion proof and unresolved exceptions.
6. Monitor outcomes, not model agreement
Accuracy against staff labels is not enough when historical labels contain inconsistent routing or weak investigations. Measure operational and member outcomes: missed deadlines, reopened cases, appeal rates, repeat complaints, unresolved transfers, correction rates, confirmed systemic issues, remediation completion and member feedback.
Break results out by product, channel, language, accessibility need, geography and other lawful review segments. Watch for under-routing as well as false alarms. A model that makes the queue look cleaner by suppressing difficult cases is not improving the system.
Evidence: outcome scorecard, segment results, human overrides, false-negative review, repeat-contact analysis and approved threshold changes.
7. Preserve an appeal, correction and no-model path
Members and staff need a clear way to challenge a category, summary, finding or proposed resolution. A reviewer should see the original record, model output, edits, evidence considered and decision owner. Corrections must update the case without erasing the earlier state.
Test the manual path at least quarterly. Staff should be able to receive, route, investigate, respond and report when the AI service, vector store or vendor is unavailable. Set stop conditions for uncited summaries, missing records, rising correction rates, deadline misses, privacy events and unexpected category drift.
Evidence: appeal route, immutable change history, correction reason, fallback procedure, exercise result, stop decision and restart approval.
A minimum complaint-control packet
Member-service, complaints, compliance and operations leaders should be able to review one compact packet containing:
- complaint volume and rate by product, channel, issue and harm tier;
- intake age, response age, resolution age and deadline exceptions;
- AI classifications, confidence, overrides and unsupported-summary findings;
- validated root causes with denominators and operational evidence;
- member remedies, affected-population counts and completion exceptions;
- reopened cases, appeals, repeat contacts and member feedback; and
- model, taxonomy, policy, product and vendor changes since the prior review.
The packet should let leaders reconstruct why a case was routed, how a cause was confirmed and whether every affected member received the approved remedy.
Run five tests before launch
- Boundary test: submit messages that are simultaneously complaints, disputes, fraud claims and service requests; confirm every required workflow starts.
- Citation test: require the system to support every material summary statement from the original record and reject uncited output.
- Root-cause test: mix similar narratives from different causes and different narratives from one cause; verify analysts do not accept the cluster at face value.
- Remediation test: seed one complaint that affects a wider population and confirm the process finds, calculates and validates the full cohort.
- Fallback test: remove the AI service, complete the case manually and preserve the full audit trail and deadlines.
AI can help a credit union see patterns sooner and spend less time moving complaint records between queues. The durable value comes from stronger investigations and faster, complete remediation—not from producing a label more quickly. Preserve the member’s original account, keep causality and authority human, and measure whether the operating system actually prevents the problem from recurring.
Turn complaint patterns into governed action. Subscribe to the CreditUnionAI Weekly Briefing for practical implementation and risk coverage.
Get the Weekly Briefing