Credit Union of Colorado has selected an AI-powered vehicle-loan pricing engine designed to move its auto portfolio beyond uniform rate sheets and toward pricing each deal on the borrower, collateral and market conditions. The November 2 announcement makes the Colorado institution an early named customer for Scienaptic AI's LendSmart Auto product.
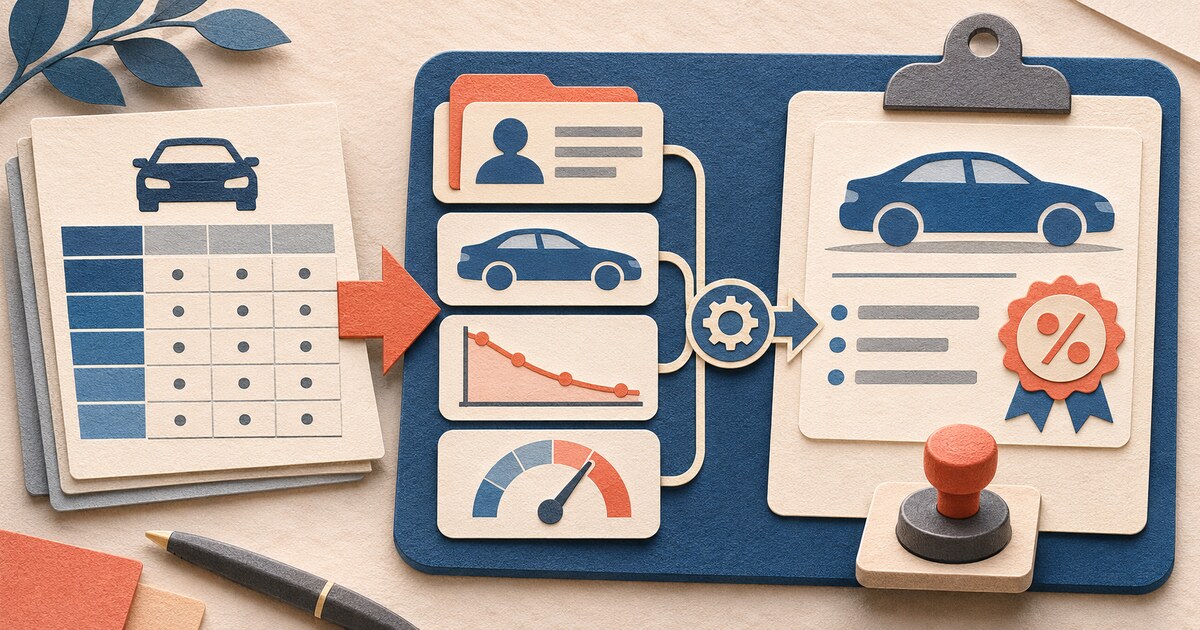
The provider says the engine adds vehicle identification number data, depreciation curves, regional resale demand, projected auction recovery and loan-to-value exposure to the credit union's borrower information. It can also incorporate Credit Union of Colorado's target return on assets and deal and operating costs.
Those inputs make the project more specific than a general AI-underwriting announcement. Traditional risk tiers group loans with similar borrower profiles under one rate. Deal-level pricing can distinguish two otherwise similar applications when the vehicles have materially different value-retention and recovery characteristics.
The announcement is a selection, however—not a reported go-live or outcome study. It does not say when the system will enter production, how many applications it will price, what data sources and update frequencies it will use, or how rates, approvals, losses and member outcomes changed.
The model is changing a member-facing term
Pricing is not merely an internal efficiency calculation. A model's output can affect the annual percentage rate a member sees, whether the member accepts the offer and how the loan performs. That puts source data, constraints, explanations and monitoring at the center of the deployment.
Credit Union of Colorado's lending team should be able to reconstruct each proposed price from the borrower data, vehicle data, market snapshot, cost assumptions, target return and policy constraints in force at that moment. If an employee changes the recommendation, the record should preserve the original price, override reason, approver and final terms.
The NCUA's AI supervision FAQs say existing rules remain technology-neutral and emphasize internal controls, ongoing monitoring and due diligence on an AI vendor's safeguards, reliability and fit with the credit union's business model. The Equal Credit Opportunity Act's Regulation B likewise continues to apply when technology influences credit terms or decisions.
Test precision against fairness and portfolio results
A credible pilot needs more than a comparison with the old rate sheet's average yield. Before activation, the credit union can replay a fixed historical sample through the new engine and compare proposed prices with realized credit losses, prepayments, recoveries and the existing policy. Data leakage, stale vehicle values and unrealistic recovery assumptions should be hard-stop failures.
In production, the monitoring set should include quoted rate, accepted rate, approval and booking rates, overrides, exceptions, delinquency, loss severity, auction recovery, spread to funding cost and complaints. Results should be segmented by protected-class proxy analysis where legally appropriate, dealer and channel, geography, vehicle age and value, borrower risk band and employee overrides. Precision that lifts yield by shifting adverse outcomes to one member group is not a successful deployment.
An industry report on the selection describes the same deal-level inputs but adds no implementation or performance evidence. The next useful disclosure will be a production date and a matched comparison showing whether individualized pricing produced better member and portfolio outcomes without widening unexplained disparities.
Our seven controls for AI-assisted loan pricing provide the evidence record for purpose, data, constraints, explanations and outcomes. The Communication Federal Credit Union go-live shows why vendor projections should remain separate from realized results.
Credit Union of Colorado's move is consequential because it puts vehicle-level economics into the rate decision. Its significance will ultimately depend on whether the credit union can show that the additional precision is explainable, fair and better for both members and the portfolio.
Follow measurable credit-union technology outcomes. Explore published CreditUnionAI Weekly web briefings for source-backed operating coverage.
Browse web briefings