Credit-union product leaders should treat PSECU's plan as a controlled member-guidance experiment, not as evidence that generative AI is ready to make financial decisions for members. The useful test will be whether staged users can understand the guidance, identify errors, reach a person when needed and take better actions without added complaints or harm.
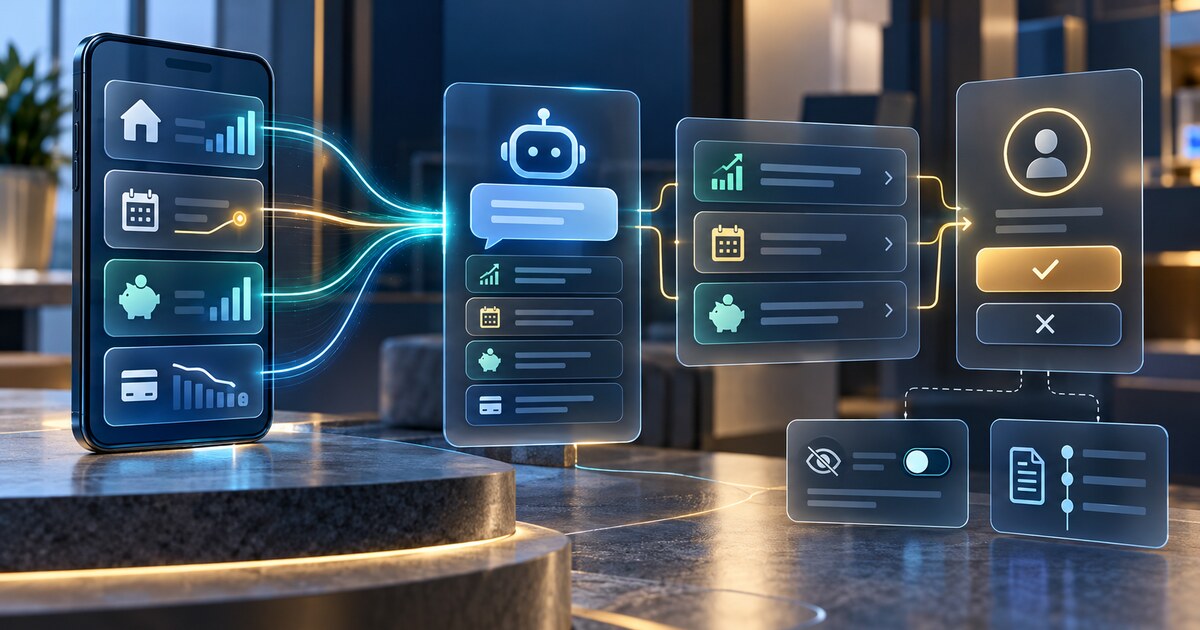
American Banker reported October 9 that Harrisburg, Pennsylvania-based PSECU plans to use Candescent's Votiv experience, powered in part by Google's Gemini models, to show members contextual summaries, upcoming cash-flow gaps and suggestions such as saving more or paying down debt. PSECU has more than 545,000 members and more than $9 billion in assets.
The project is planned, not broadly live. PSECU told the publication that it will begin with employees, friends and family, use their feedback to find errors and expand gradually. It has not set a public rollout date. Members are expected to take the action themselves, and the current roadmap does not allow the model to move money automatically between accounts. The credit union also plans an opt-out.
PSECU acknowledged that the model will not always be accurate and said governance and feedback mechanisms are in place. Those statements set an appropriate direction, but they are not measured production results. The article did not report accuracy, complaint, adoption, financial-outcome or member-harm rates.
Separate guidance from execution
Keeping money movement outside the initial experience is an important boundary. A summary can be reviewed and ignored; an autonomous transfer changes a member's financial position. Credit unions evaluating similar tools should define the launch boundary in writing: what the model may summarize, what it may recommend, which source records support the answer, and which actions always require a member or employee decision.
The source evidence also needs to remain visible. A warning about a cash shortfall should link to the bills, balances and timing assumptions behind it. A savings suggestion should not imply certainty about income, liquidity or competing obligations. When the model is unsure or the data are incomplete, the interface should say so and offer a clear route to staff assistance.
Candescent said in August that Votiv will use Gemini to power contextual summaries, actionable insights and proactive intelligence across its platform. That is a vendor description of planned capability, not independent evidence of performance. Credit unions should validate the exact configuration they receive, including prompt and model changes, data access, retention, monitoring and rollback.
Use the controlled cohort to set evidence thresholds
PSECU's employee-and-family phase can do more than collect impressions. The institution can define a test set of common member situations, record the source data each answer used, compare outputs with approved guidance, and classify errors by consequence. A wrong category label is different from advice that could cause an overdraft, missed payment or unsuitable product choice.
Before wider release, management should have thresholds for factual accuracy, unsupported claims, escalation success, member comprehension, opt-out completion and complaint handling. It should also compare outcomes between people who saw guidance and a matched group who did not. Engagement alone cannot show whether the service improved financial health or simply generated more clicks.
Make member choice auditable
An opt-out is meaningful only if members can understand what they are leaving, complete the choice easily and receive a consistent experience across mobile, web and assisted channels. Product teams should retain the consent state, the version of the guidance experience shown, the model and policy version, the source evidence, any human escalation and the resulting member action.
PSECU's own September 29 announcement described a multi-year transformation and joint implementation with Candescent. Candescent's Google Cloud announcement says the platform will use Gemini models across member and employee experiences. Together, those sources establish the planned architecture; the staged rollout now needs to establish whether the member experience is accurate, understandable and useful.
For credit unions, the immediate lesson is not to copy the feature list. It is to copy the discipline of a limited cohort, preserve human action and opt-out controls, and require evidence before expanding access or authority. Our coverage of another planned AI money coach and contact-center quality controls provide additional tests for member-facing AI.
Track consequential changes in member experience, technology and governance. Explore published CreditUnionAI Weekly web briefings for source-backed coverage.
Browse web briefings